


One Liquidity Strategy, Many Venues: How THEO Connects CEX and DEX Markets
One Liquidity Strategy, Many Venues: How THEO Connects CEX and DEX Markets
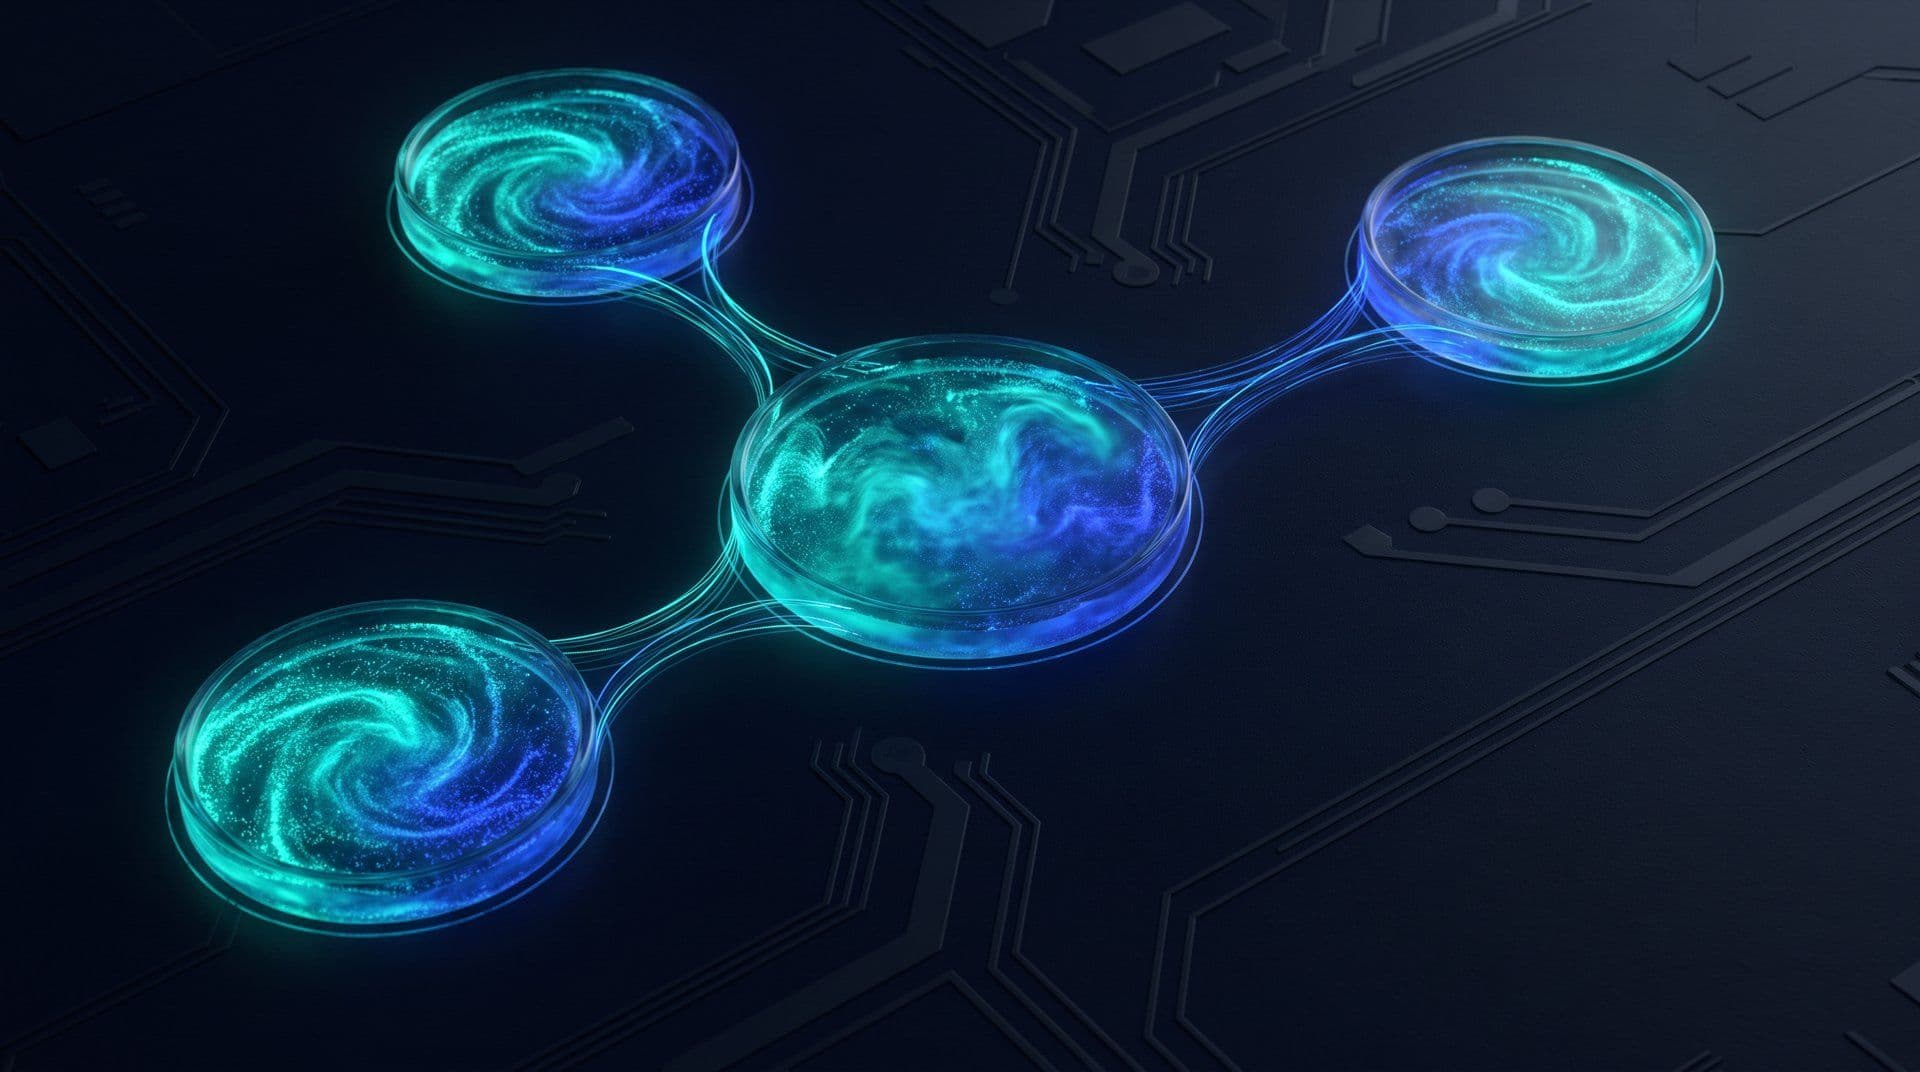
What happens to liquidity when a coin trades on an order book and three AMM pools at the same time? Without coordination, it fragments. Each venue develops its own depth, its own spread, and its own price, and traders pay for the gaps between them. Autheo's answer is to treat every THEO market as part of one liquidity system, managed by a single partner, rather than as separate pools that happen to share a ticker.
This is Part 2 of our four-part MEXC series. Part 1 explained what MEXC is and why centralized access complements THEO's decentralized markets. Today covers how liquidity works across all of those venues together.
Key Takeaways
From October 1, THEO is scheduled to trade across four markets: Hydrex on Base, two Uniswap pools on Robinhood Chain, and MEXC.
Fragmented liquidity leads to wider spreads, price gaps between venues, and higher costs for traders.
Enflux manages THEO liquidity across both centralized and decentralized venues under one mandate.
Active range management on Uniswap v3-style pools keeps liquidity concentrated where trading actually happens.
Arbitrage naturally links prices across venues, and coordinated liquidity makes that linkage smoother.
Users should still check depth and slippage on the specific venue they plan to use.
The Venue Map
THEO's decentralized markets launched in stages. THEO / USDC opened on Hydrex on Base on August 20, 2026, which we covered in THEO's token generation event and Hydrex listing. On September 10, THEO / USDG opened on Uniswap v3 on Robinhood Chain.
On September 24, THEO / NVDA went live through Uniswap on Robinhood Chain, pairing THEO with a tokenized NVIDIA instrument. Our post on THEO's two new markets explains that pairing and the Stock Token disclosures that come with it. On October 1, THEO is scheduled to add MEXC, its first centralized order book.
That gives THEO three different quote assets and two very different market structures. USDC and USDG are dollar stablecoins, NVDA is a tokenized equity instrument, and MEXC will quote against its own supported pairs. Each one attracts a different kind of trader.
Stablecoin pairs tend to draw people who think about THEO in dollar terms and want a simple entry or exit. The NVDA pair draws people who already hold tokenized equity exposure and want to move between it and THEO without passing through a stablecoin first. MEXC draws account-based traders who prefer order books, limit orders, and a familiar exchange interface.
Why Fragmentation Is the Real Risk
Every new venue adds reach, but it also splits liquidity. If the same total depth is divided four ways without coordination, each individual market becomes thinner. Thin markets mean larger price impact on each trade and more room for venues to drift apart.
The industry data shows why this matters. The CoinGecko 2026 CEX and DEX report found DEX share of spot volume climbing from 6.9 percent in January 2024 to 13.6 percent in January 2026. As volume spreads across both venue types, projects that trade in both places need a plan for keeping them connected.
Arbitrage does part of that work automatically. When THEO is cheaper on one venue than another, traders buy low and sell high until prices converge. But arbitrage is only efficient when each venue has enough depth to absorb those trades without large slippage.
There is also a timing problem. Centralized order books update in milliseconds, while onchain pools update only when transactions land in a block. When prices move quickly, the gap between an exchange quote and a pool price can widen before arbitrage closes it, and traders on the thinner venue feel it first.
What a Coordinated Liquidity Partner Does
Autheo has engaged Enflux, a quantitative trading and liquidity firm, to manage THEO liquidity across its full market ecosystem. We introduced that relationship when Autheo engaged Enflux ahead of the Hydrex listing. The mandate now covers Base, Robinhood Chain, the THEO / NVDA market, and MEXC.
On centralized order books, a market maker quotes both sides of the book continuously, which narrows spreads and adds visible depth. On AMMs, the work looks different. Enflux's decentralized practice includes active range management and rebalancing on Uniswap v3-style pools rather than relying only on static positions.
"As THEO expands across decentralized and centralized markets, the objective is to maintain a consistent liquidity strategy across each environment," said Evgeni Hristov, Head of Trading at Enflux. "Supporting THEO across Base, Robinhood Chain, and MEXC allows us to manage those markets as parts of a broader liquidity ecosystem rather than as isolated venues."
Why Range Management Matters on Uniswap v3
Uniswap v3 introduced concentrated liquidity. Instead of spreading capital across every possible price, liquidity providers choose a price range where their capital is active. Inside that range, the same capital provides much deeper liquidity than a traditional full-range pool.
The tradeoff is maintenance. If the market price moves outside the chosen range, that liquidity stops earning fees and stops supporting trades until someone repositions it. Active range management is the discipline of watching those ranges and rebalancing them as the market moves.
Done well, it keeps capital working near the current price, where most trades happen. Done poorly, or not at all, a pool can look well funded on paper while offering little real depth at the price that matters. That difference is invisible on a simple total value locked figure, which is why active management matters more than headline pool size.
This is also why a single partner across venues helps. The same team that sees order flow on MEXC can adjust ranges on Robinhood Chain and Base, instead of three separate teams reacting to each other after the fact. Coordination turns four markets into one picture.
For THEO, this matters across two Robinhood Chain pools at once. The USDG pool tracks a dollar reference, while the NVDA pool tracks a tokenized equity that itself moves with NVIDIA's price. Our guide to why tokenized stock prices and liquidity differ from real shares explains why that second pool behaves differently from a stablecoin pair.
How the Pieces Fit Together
Think of THEO's markets as one system with four entry points. A trader in Southeast Asia might reach THEO through MEXC. A DeFi user on Base might use Hydrex, while a Robinhood Chain user might trade the USDG or NVDA pool from the same wallet.
When those markets are managed together, activity on one venue informs positioning on the others. That reduces the chance that one pool drifts far from the rest, and it helps each venue carry enough depth for ordinary trade sizes. The goal is not identical prices at every second, which no multi-venue asset achieves, but a tight and predictable relationship between them.
Robinhood Chain's growth makes this more relevant. Galaxy Research's analysis of the Robinhood Chain launch noted mainnet went live on July 1, 2026, with Stock Tokens available in more than 120 countries and total value locked above $300 million within the first weeks. For more background, see our explainer on the ecosystem forming around Robinhood Chain.
What This Means for Everyday Users
For most users, a coordinated strategy shows up as three things. Spreads should stay reasonable on each venue, price gaps between venues should close quickly, and ordinary trades should not move the price dramatically. None of that is guaranteed, and market conditions can change quickly, especially in the first days after a new venue opens and during periods of broad market stress.
Practical habits still matter. Check the quoted price impact before you confirm a DEX swap, set a sensible slippage tolerance, and compare the order-book depth on MEXC before placing a large order. If you are new to AMMs, our developer guide to liquidity pool mechanics explains how price impact is calculated.
The Bigger Picture
Liquidity is the market side of the story. The network side is what gives that liquidity a reason to exist. Autheo Mainnet has been live since May 14, 2026, with staking and transaction fees live today and compute, storage, and AI inference utility rolling out over the coming months.
"Liquidity without infrastructure is just a market," said Todd Mortenson, Founder and Managing Director of Autheo. "Infrastructure without liquidity is just a network."
That balance is the thread running through this series. If you are new to the project, start with our complete guide to Autheo.
Over time, the aim is for more of THEO's market activity to reflect real usage of the network. As DevHub and the Autheo Infrastructure Marketplace roll out over the coming months, applications are designed to consume infrastructure and settle that activity in THEO. Coordinated liquidity makes sure the markets are ready when that demand arrives.
Tomorrow, Part 3 looks at where MEXC's reach extends, from Southeast Asia and Eastern Europe to Latin America and the CIS, and why those regions matter for a network built by contributors in more than 25 countries.
In the meantime, verified trading links and contract addresses live on the official Autheo token launch page. Nothing in this post is investment, legal, tax, or financial advice. Explore the network behind the markets at autheo.com.
Gear Up with Autheo
Rep the network. Official merch from the Autheo Store.

AUTHEO Gradient Everyday Carry Tote Bag
$30.50

AUTHEO Pom-Pom Beanie
$25

AUTHEO Large Organic Tote Bag
$30

AUTHEO Notebook
$22.50
Theo Nova
The editorial voice of Autheo
Research-driven coverage of Layer-0 infrastructure, decentralized AI, and the integration era of Web3.
About this author →Get the Autheo Daily
Blockchain insights, AI trends, and Web3 infrastructure updates delivered to your inbox every morning.